New York Life
Life Insurance Transformation
Data, digital distribution, changing buyers and the future of financial protection.
From pricing the past to architecting risk.
For more than three decades, Jim Carroll has helped insurers, reinsurers, brokers, actuaries, benefits organizations and corporate risk leaders understand what happens when the velocity and complexity of risk change faster than the industry built to manage it.
Insurance spent centuries pricing the past. The industry now has to price the present, anticipate what comes next and increasingly prevent risk before it becomes a loss.
Detect new risk categories, changing behaviour and connected exposure sooner.
Move from historic averages toward predictive signals, continuous monitoring and intervention.
Build agility, insight and execution into an industry where the assumptions underneath the model keep changing.
Technology changes underwriting and claims. Leadership determines whether the organization can change with them.
Jim has worked with insurance CEOs, CIOs, COOs, actuaries, distribution leaders, brokers and corporate risk executives for decades. The leadership question is not merely what is changing. It is what must we do differently because risk, technology and customer expectations are changing?
These are not canned speeches. They are possible directions selected and blended around the insurance segment, leadership team, audience and strategic issues in the room.
From pricing the past to architecting risk.
Underwriting, claims and risk in the intelligent era.
When risk accelerates faster than the models built to understand it.
From historical actuarial models to continuous risk assessment.
Reinventing human value in a direct, digital world.
Agility, insight and execution for insurance leadership.
Five strategic lenses for understanding what real-time information, AI and connected risk do to the insurance business model.
See emerging exposure and loss patterns earlier.
Use current, granular and behavioural data.
Intervene before risk becomes a claim.
Build products around real context and behaviour.
Become a risk-management partner, not merely a claims payer.
Connected risk turns insurance into an ongoing service.
Homes, vehicles, industrial assets, buildings, health devices and cyber systems increasingly report conditions continuously. That creates the opportunity to identify risk earlier, intervene sooner and potentially prevent loss altogether.
Underwriting increasingly moves from static snapshots toward continuous risk signals and AI-assisted decisions.
Combine traditional data with current behavioural, spatial and connected-device information.
Accelerate routine decisions while escalating exceptions to human judgement.
Reassess exposure as conditions change rather than only at renewal.
Blend geography with property, crime, climate, infrastructure and community data.
Identify concentration and emerging exposure earlier across a book of business.
Use AI to increase speed and pattern recognition without abandoning judgement or governance.
AI and connected data can automate first notice of loss, image-based damage assessment, triage, fraud analytics, straight-through processing and catastrophe response.
But as AI gets better at creating evidence, insurance must get better at validating reality.
Deepfake imagery, synthetic identity, generated documentation and automated fraud operations create a new AI-versus-AI contest.
Risk appears faster, spreads faster, compounds faster and invalidates models faster.
Wildfire, flood, hurricane, heat and rebuilding costs challenge assumptions about property risk.
Adaptive threats turn cyber from a technology issue into financial, operational and physical risk.
AI liability, autonomous systems, synthetic biology, quantum risk and new energy systems create categories that may not yet fit existing models.
Behaviour becomes a risk signal.
Jim was describing telematics-driven auto insurance years before usage-based insurance became mainstream. The same idea now extends to commercial fleets, equipment, health behaviour and temporary or contextual coverage.
Wearables, health records, wellness data, predictive health, accelerated underwriting and longevity science increasingly connect insurance to measurable behaviour and changing health status.
Jim was describing performance-oriented insurance and bio-connectivity long before they became mainstream industry themes.
Digital channels expose where human value really exists.
Digital simplicity resets expectations for buying, servicing and changing insurance.
The policy disappears into the car, trip, payment, device, home or platform.
Complexity, advice, advocacy, specialization and relationship become more valuable as routine transactions become digital.
Insurance expertise gets more specialized at exactly the moment the underlying risk environment becomes more complex.
Translate environmental change into exposure and pricing insight.
Price threats that evolve continuously and strategically.
Understand algorithmic liability, governance and model risk.
Build products around measurable triggers rather than traditional claims processes.
Jim's insurance work predates insurtech, AI underwriting and the connected-device economy.
Internet disruption, online distribution, privacy, security and changing broker relationships.
Technological risk, underwriting complexity, customer empowerment and agility.
Telematics, bio-connectivity, predictive analytics, usage-based products and insurtech.
Automated underwriting, cyber, climate, fraud, embedded insurance and real-time risk data.
Insurance evolves from transferring risk toward helping clients anticipate, reduce and manage it continuously.
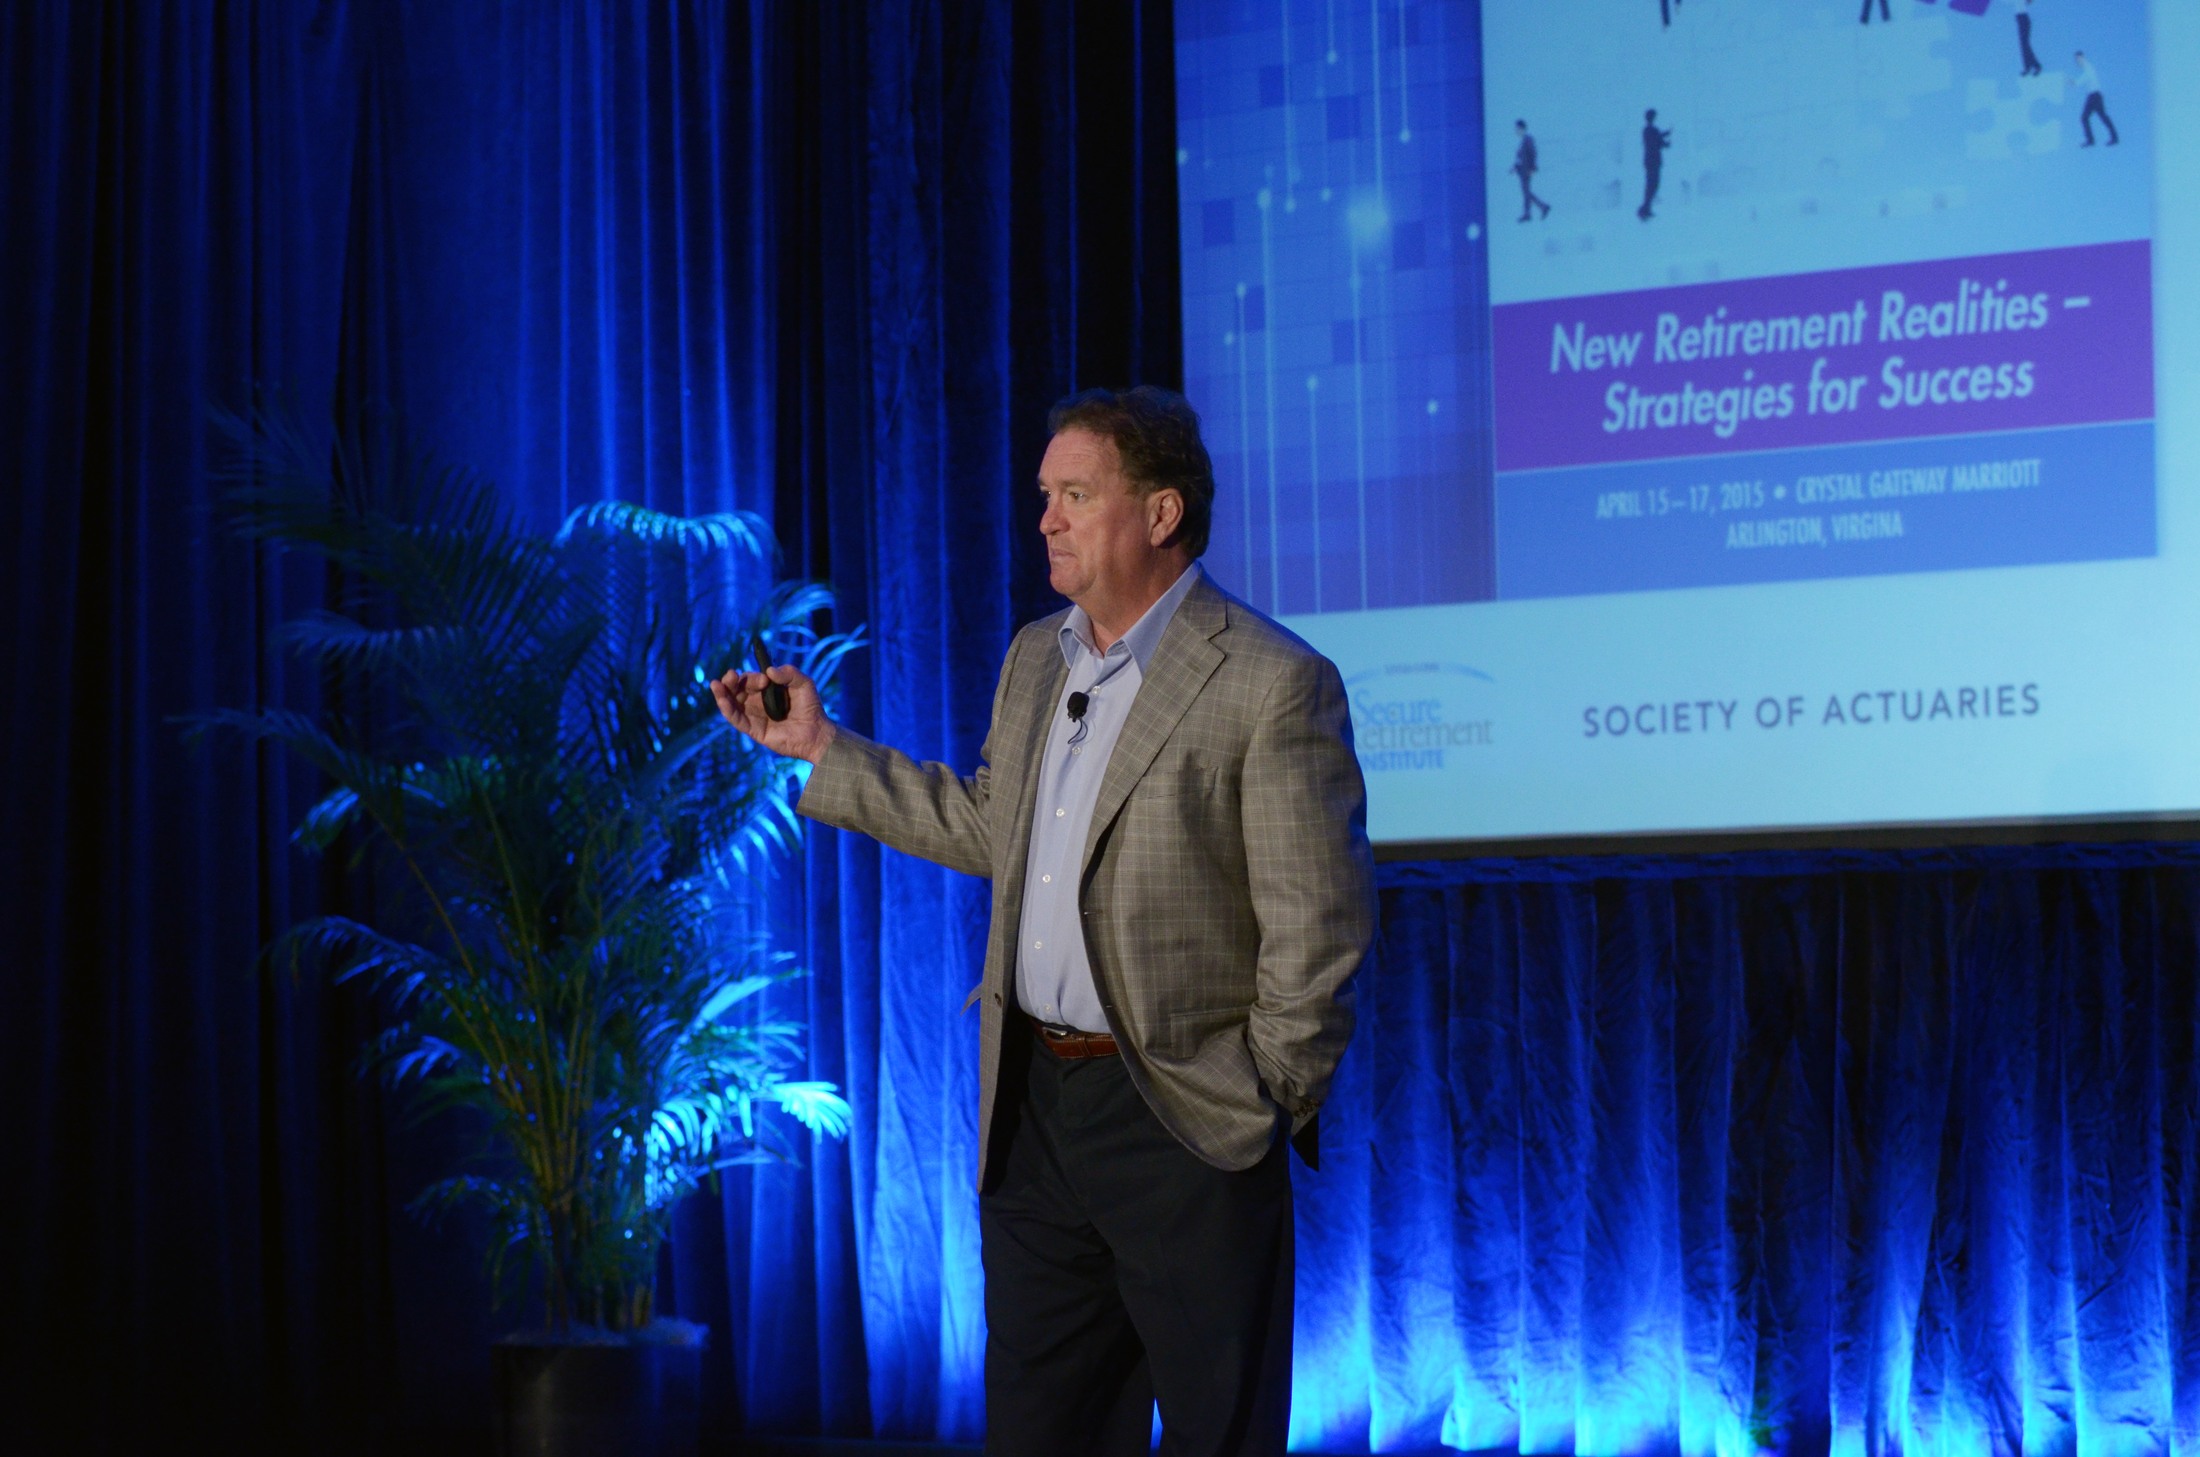
A useful futurist leaves receipts.
Faster science and change would create new niche skills and harder risk assessment.
Auto insurance would increasingly price actual driving behaviour.
Measurable wellness behaviour would influence insurance economics.
Wearables and health data would reshape life underwriting and engagement.
Predictive analytics would push the industry toward real-time coverage.
AI would accelerate underwriting, claims, fraud analysis and the emergence of new risk itself.
A sampling of the insurers, reinsurers and risk organizations Jim has worked with.
More client logos being added.
Life insurance, P&C, reinsurance, risk management and industry leadership require very different future stories.
Data, digital distribution, changing buyers and the future of financial protection.
Accelerated risk, AI, post-pandemic volatility and the leadership challenge of managing uncertainty.
Life insurance, insurtech disruption, trust, distribution and evolving customer expectations.
Private leadership discussions with senior executives across major global carriers on future risk, underwriting and disruption.
How insurers can become broader risk partners as complexity and connectivity accelerate.
Property/casualty, life, brokers, actuarial, benefits and reinsurance audiences across decades of industry change.
Jim has addressed major carriers, associations and closed-door executive groups throughout the global insurance industry.
P&C / General Insurance: Chubb • Farmers • Gore Mutual • Economical Insurance • Assurant • Zurich • Hartford • FM Global
Life & Financial Protection: New York Life • Sun Life • Manulife • RBC Insurance • MetLife • Lincoln Financial • Equitable • RGA Reinsurance
Health / Benefits: Cigna • Blue Cross Blue Shield • Harvard Pilgrim • Providence Health Plans • Magellan Health • New York Health Plans Association
Brokers / Reinsurance / Actuarial: Brokers & Reinsurance Markets Association • Independent Insurance Agents • LIMRA • GAMA • actuarial organizations • Insurance Institute of Canada • Verisk
Closed-door C-suite sessions have included leaders from: Allianz • AIG • Travelers • AXA • Allstate • Liberty Mutual • The Hartford • State Farm • Progressive • GEICO • Nationwide • Farmers • CNA • Generali • Ping An • Lloyd's of London • XL Insurance • American Family • RSA.
Because a life insurance CEO does not need the same future as a P&C underwriter, reinsurer, broker or benefits organization.
Client calls, market reports, regulatory and technology analysis, current news, audience issues and segment-specific examples. Jim's existing insurance site notes that his broader research process can involve accessing thousands of highly relevant articles and reports.
LISTEN → RESEARCH → MAP THE RISKS → BUILD THE STORY → CONNECT THE ROOM → LEAVE A PLAYBOOK
Tell Jim who is in the room, which part of the industry they represent, what is changing around them and what you want them thinking about when they leave.
P&C? Life? Reinsurance? Broker? Benefits? Corporate risk?
Risk? AI? Underwriting? Distribution? Climate? Leadership?
Research, stakeholder calls, agenda integration and segment-specific insight.
Timing, format, fees, travel, logistics and the best next step.
Jim is always pleased to jump on a quick exploratory Zoom or phone call to learn more about the audience and talk through possibilities.
Contact JimGrab the PDF